Why standard Bitcoin transfer figures are off by up to six times, according to the BIS
Public blockchains record every transaction, yet researchers can derive multiple measures of economic activity from the same transparent ledger.
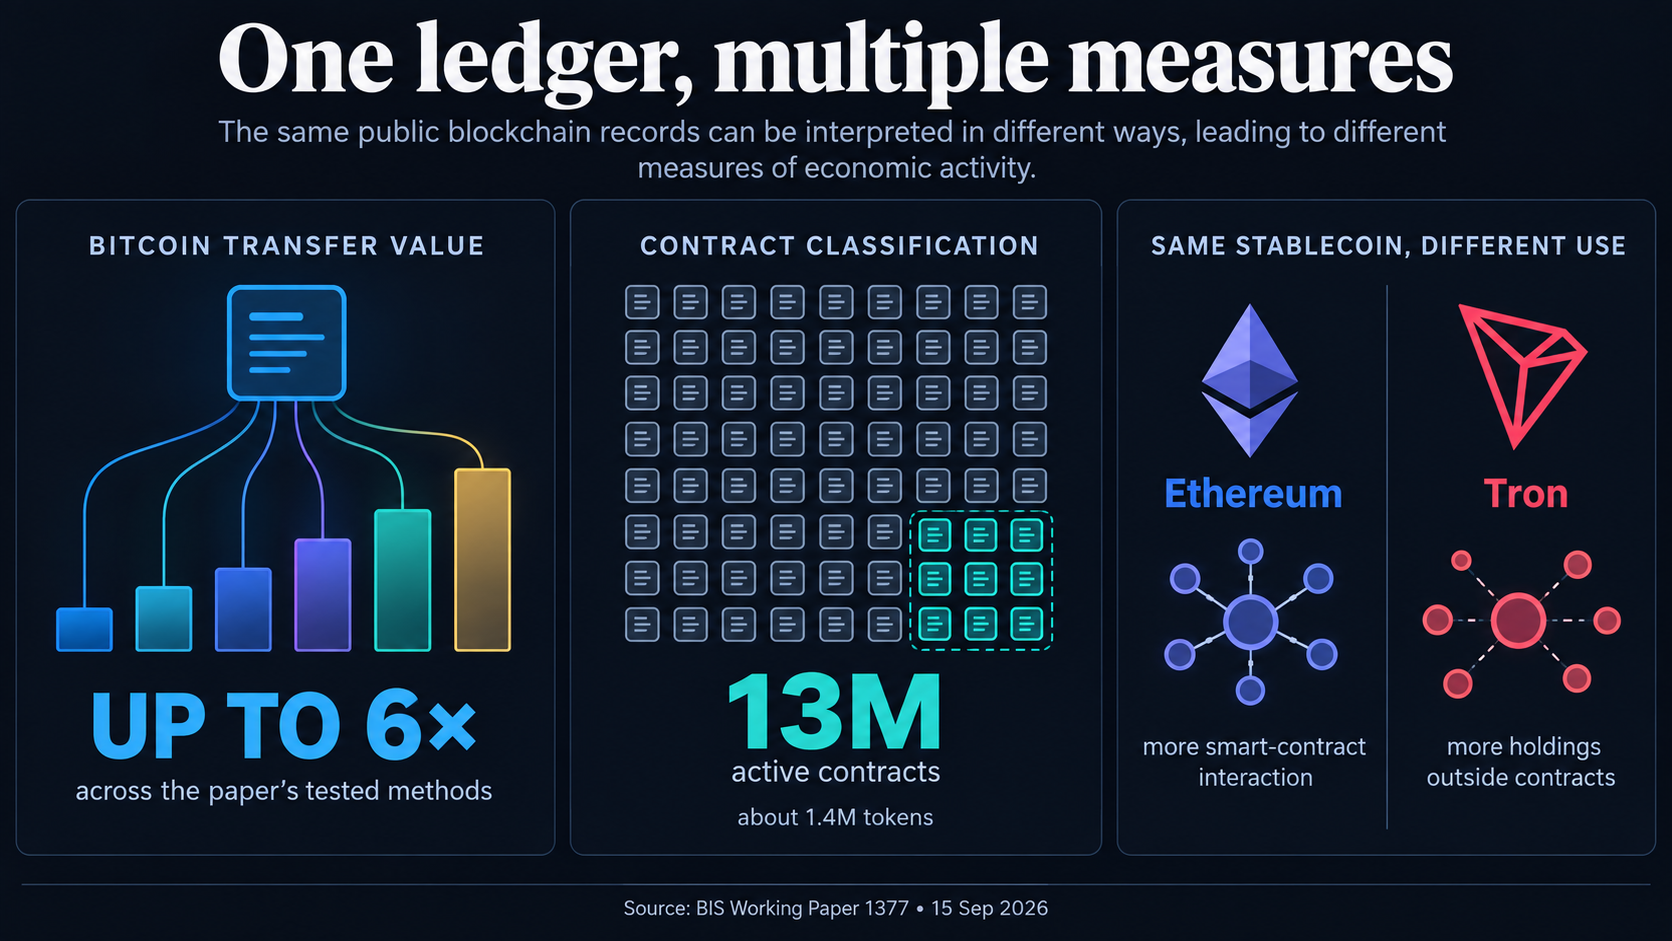
A Bank for International Settlements (BIS) working paper published Sept. 15, found that Bitcoin transfer-value estimates differed by as much as a factor of six across the measurement approaches tested. That result is specific to the tested approaches rather than a universal sixfold error. It shows that totals can change sharply when analysts make different choices about how technical blockchain records should be translated into economically meaningful transfers.
For Bitcoin, measurement turns on how recorded movements are grouped and interpreted when calculating value transferred. The paper identifies transaction aggregation as one of three structural sources of measurement divergence, alongside smart-contract programmability and comparisons of activity across blockchains.
A chart can apply its chosen calculation consistently while still reflecting assumptions that are invisible in the headline total. The authors' wider point is that the ledger supplies the records, while researchers decide which records represent comparable economic events.
Contracts and stablecoins complicate comparisons
The paper uses smart contracts and cross-chain stablecoin behavior to show how the same classification problem extends beyond Bitcoin.
The authors classified 13 million active contracts, including about 1.4 million tokens, and said extensive token issuance and rapid contract proliferation make economically meaningful activity harder to identify. The paper also found trading activity was highly concentrated and centered around stablecoins.
Stablecoin figures also differed in economic meaning across networks. The same stablecoin reflected different economic uses depending on the blockchain. On Ethereum, stablecoin activity was more closely associated with smart-contract interactions. On Tron, stablecoins were more commonly held outside smart contracts, a pattern the authors described as consistent with transactional and store-of-value motives.
Those differences mean cross-chain activity rankings can blur distinct forms of behavior when every recorded unit is treated as economically equivalent. Public data still requires assumptions that connect technical events to economic activity.
The authors argue that on-chain indicators should therefore be read as noisy approximations rather than direct measures of economic activity. They propose granular, data-bounded estimates that make assumptions explicit and use technical classification and disaggregation to connect ledger events with economic meaning.
For readers, the practical takeaway is that an on-chain figure is most useful when its methodology is visible. Transfer value, active contracts and stablecoin holdings can illuminate network behavior, but comparisons remain dependent on the counting rules behind them.
The publication attributes the conclusions to its authors and distinguishes them from official BIS views.