Strategy’s daily dividend proposal puts Bitcoin funding back in investors’ hands
The @saylor account said Friday that Strategy wants to pay dividends daily on four of the preferred shares it uses in its Bitcoin financing strategy. The proposal would put cash in holders' hands sooner without changing the securities' economics at their current rates. Its value to Strategy depends on whether investors will pay more for that timing.
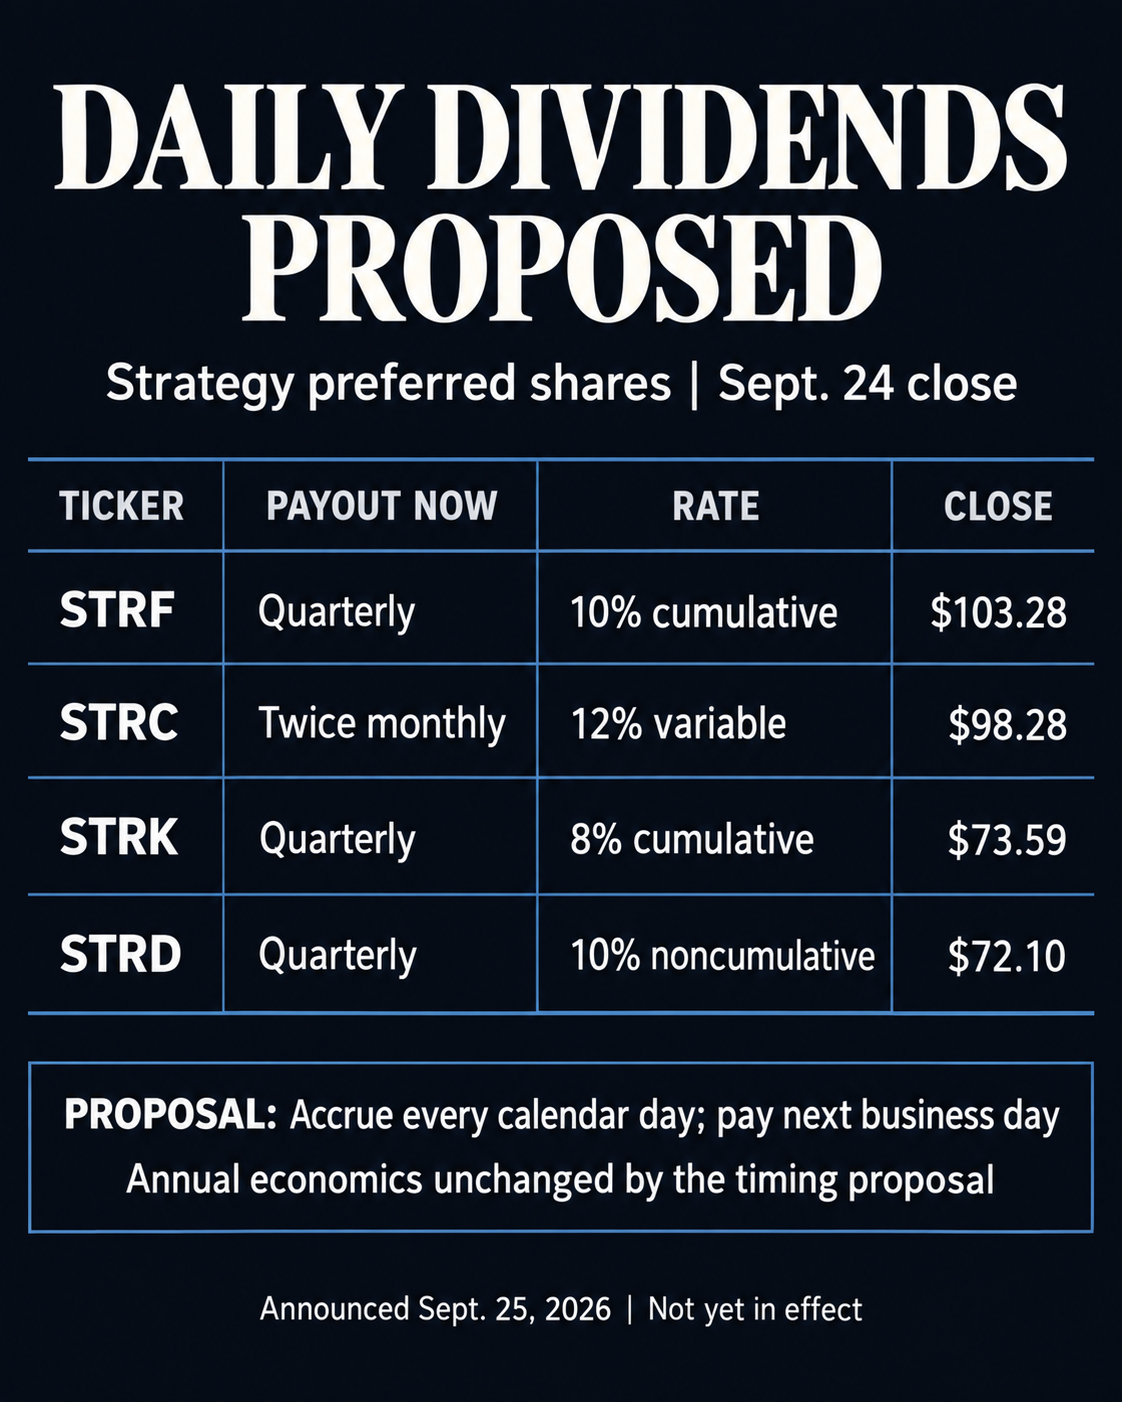
The hurdle differs across the four shares. At Thursday's close, before the proposal, STRF traded above $100 and STRC was close to it, while STRK and STRD were in the low $70s. Those prices are a trading baseline, not evidence that daily payment will lift demand or that Strategy could issue new shares at the same prices.
According to the post, dividends on STRF, STRC, STRK and STRD would accrue every calendar day, including weekends and holidays, and be paid the next business day. It did not specify daily record dates, an effective date or the series-by-series approvals. Strategy's August 31 dividend declaration still sets quarterly payments for STRF, STRK and STRD and twice-monthly payments for STRC.
A faster calendar does not equal the same claim
Strategy's preferred-stock disclosure draws a sharper distinction than payment frequency. Dividends on STRF, STRC and STRK are cumulative, meaning unpaid amounts can accrue under their terms. STRD's are noncumulative: an omitted regular dividend does not become an arrears claim. Payments across the four series remain subject to board declaration and legally available funds. STRK may pay a declared dividend in cash, MSTR shares or both.
| Security | Current payment cadence | Annual dividend rate | Sept. 24 close | Sept. 24 volume |
|---|---|---|---|---|
| STRF | Quarterly | 10%; cumulative | $103.28 | 20,313 shares |
| STRC | Twice monthly | 12% at the latest declaration; variable and cumulative | $98.28 | 1,023,834 shares |
| STRK | Quarterly | 8%; cumulative | $73.59 | 69,162 shares |
| STRD | Quarterly | 10%; noncumulative | $72.10 | 93,762 shares |
The rates and rights come from Strategy's filings; its August 31 report set STRC at 12% annually for semi-monthly periods beginning September 16. The closing prices and share volumes are the September 24 regular-session figures reported by ChartExchange. A single day's volume does not establish lasting liquidity.
The $100 line is a comparison point, not a uniform legal par or guaranteed redemption price. In its June 30 filing, Strategy listed $0.001 legal par for these securities and no $100 stated amount for STRK, although it reported a $100 liquidation preference for STRK at that date. The other series also have their own preferred terms.
Under the August 31 declaration, holders of record on September 15 are due $2.50 per STRF share, $2 per STRK share and $2.50 per STRD share on September 30, as well as $0.50 per STRC share. Another $0.50 STRC payment is due October 15 to holders of record on September 30. The two STRC payments each represent a 12% annualized rate. The daily proposal has not replaced those declared dates.
STRC's last schedule change shows that a faster calendar can leave the dividend obligation intact. Majorities of common and STRC holders approved its move from monthly to twice-monthly record and payment dates on June 8. The June 30 filing says that change took effect that day without increasing the company's dividend obligation. That precedent does not settle what approvals or amended terms the proposed daily payments would need for all four series.
The Bitcoin financing test
More frequent cash receipt could make a preferred share more attractive. If that translates into sustained buying and firmer trading prices, new preferred issuance could become more attractive to Strategy as a way to raise capital for its Bitcoin strategy. This is a conditional market effect, not a higher annual rate or a stronger legal claim. The September 24 prices and volumes cannot show a reaction to a September 25 proposal, much less proceeds from a future offering.
Strategy's September 21 cash update shows why demand for new securities matters even with a large reserve. As of September 20, its USD Reserve, intended for preferred dividends and debt interest, stood at $5.04 billion. A separate $1.05 billion of USD Cash was available for broader treasury uses. During the previous week, $57.4 million of reserve money paid preferred dividends and interest. Strategy used USD Cash to repurchase $174 million of STRC and buy 950 Bitcoin for $75.7 million. It reported no at-the-market share sales that week and said $875.1 million of preferred-share repurchase authority remained.
The buyback supported existing STRC shares in the market; it was not new financing from investors. Daily distributions might improve demand for future preferred sales, but the next useful evidence is specific amended terms and approvals, followed by prices, sustained trading and actual issuance after any change takes effect. Until then, the proposal changes the payment timetable on paper, while the funding benefit remains unproved.