Monument Bank puts £250M on Midnight, but hides strict bank rules
Quick Take
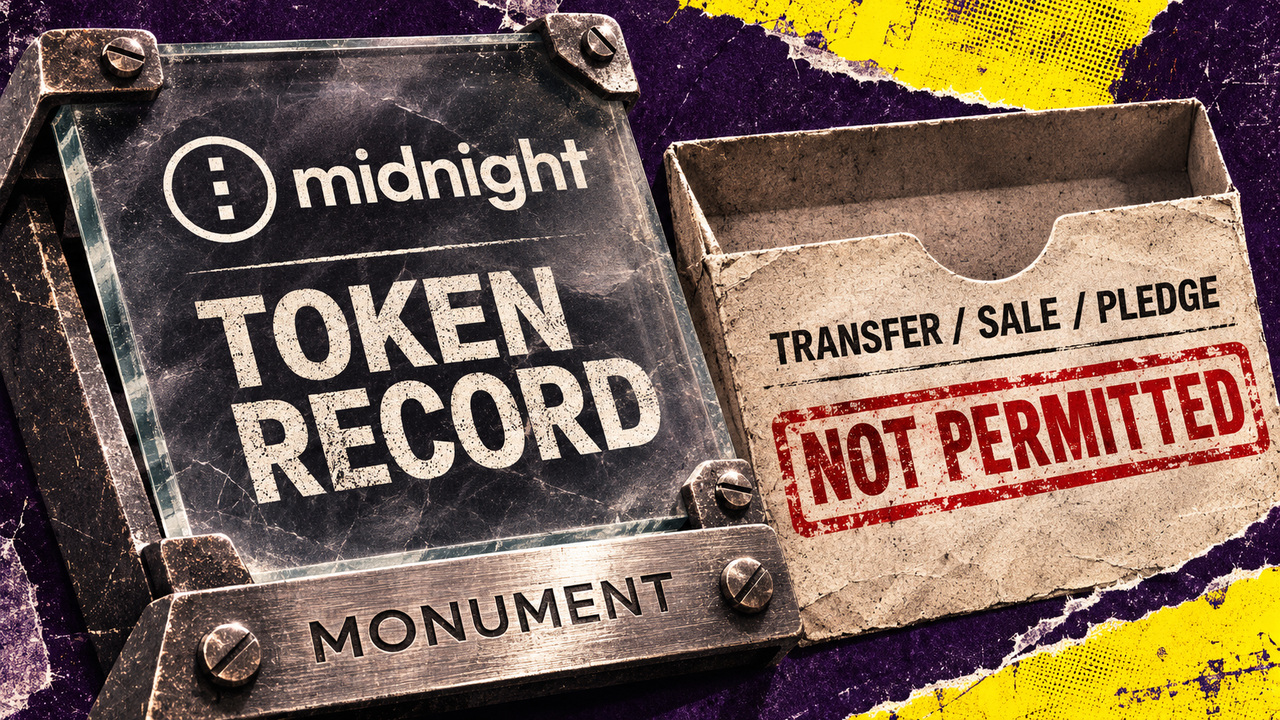
- Monument’s Tokenised Saver mirrors a fixed-term deposit on Midnight, but customers cannot transfer or pledge the token record.
- Monument’s announced £250 million target is separate from an aggregate funded balance, which its reviewed bank pages do not disclose.
- Monument can pause tokenization without changing deposit terms, while future investment and lending products remain separate from the current saver.

Monument Bank’s Tokenised Saver records customers’ deposits on the Midnight blockchain, but savers cannot transfer the token, sell it to another customer, or pledge it to an outside lender.
In a Nov. 17 post, Charles Hoskinson celebrated the bank’s launch, quoting Midnight's congratulations to Monument and its partners:
“250 million pounds on-chain! That's some serious TVL.”
Monument’s March 27 announcement described a target of up to £250 million in client deposits, so the immediate test is what a customer can do with the record today. Monument’s blockchain record leaves withdrawal and collateral rights governed by the bank’s account terms.
The bank’s record on Midnight decides
The Tokenised Saver summary says the token mirrors the deposit, while Monument’s records remain the official account of the savings. If the two differ, the bank’s records apply, subject to correcting errors. Customers retain the right to query or challenge an error.
Neither the account nor its token record may be transferred, sold, or assigned, including to another Monument customer. Monument’s FAQ also says the bank owns and controls the wallet, so customers do not manage a private key or seed phrase.
The token record cannot be used as security, while the savings account can serve as security only in Monument’s favor, with the bank's written agreement. That leaves room for an agreed bank arrangement, but supplies no right to take the token to another lender.
One deposit. A bank-controlled copy.
Monument’s savings contract supplies the rights. Its Midnight token record mirrors the deposit without adding transfer or collateral rights.
What if the token feature stops?
The bank controls the token record. The underlying deposit and its agreed terms remain authoritative.
The token feature can stop while the bank deposit continues on its agreed terms.
Current product summary and FAQ as read November 17, 2026. A paused feature is a possible contractual state, not a reported outage. FSCS cover applies to eligible deposits under aggregate limits. No issued balance or flow size is depicted.
Sources
Supporting facts
- Monument’s token record mirrors the customer’s deposit on Midnight; the bank’s own records remain authoritative if the records differ, subject to error correction and the customer’s right to challenge an error. [1] [2]
- The Tokenised Saver summary says the token record grants no rights of its own; customer rights derive from the deposit and the bank’s terms. [1]
- Under Monument’s current summary terms, customers cannot transfer, sell or assign the savings account or its token record, even to another Monument customer. [1]
- Monument prohibits use of the token record as security; the savings account itself can be used as security only in Monument’s favour by written agreement. [1]
- Monument’s FAQ says it owns and controls the wallet for the customer; the customer cannot transfer the token record and does not manage a private key or seed phrase. [2]
- Monument may change, pause or stop tokenisation, and warns that token records can be delayed, unavailable or wrong; its summary says the deposit, rate, interest, maturity and FSCS protection remain unchanged. [1] [2]
- Monument says eligible deposits have FSCS protection up to £120,000 per person aggregated across all eligible deposits with the bank; tokenisation creates no additional allowance. [1] [2]
Method
Schematic of the contractual relationship between a deposit and its mirrored record, not a transaction sequence. The selectable pause/stop state illustrates a power described in current terms.
Scope
Current product summary and FAQ as read November 17, 2026. A paused feature is a possible contractual state, not a reported outage. FSCS cover applies to eligible deposits under aggregate limits. No issued balance or flow size is depicted.
 CryptoSlate
Monument can also change, pause or stop the tokenization feature. Its summary warns that the record can be delayed, unavailable, or wrong, while saying the deposit, interest rate, interest, maturity date, and FSCS protection remain the same.
The bank deposit continues independently of whether its digital copy is functioning.
The product currently advertises a 12-month term at 5.2% annual equivalent rate, or 5.08% gross, with interest calculated daily and paid monthly. Interest can go to the customer’s linked account or back into the saver.
Eligibility is limited to existing Monument clients who are UK residents aged 18 or older. Accounts are held in one person’s name and require a personal UK bank account linked to the account.
Customers must hold at least £25,000 across Monument savings accounts, while the Tokenised Saver maximum is £100,000, excluding interest.
Customers have 14 days from account opening to fund the account and can cancel without penalty during that window. Otherwise, withdrawals and early closures are prohibited during the term, which begins with the first deposit.
Monument says eligible deposits are protected by the Financial Services Compensation Scheme up to £120,000 per person, aggregated across eligible deposits with the bank.
Lending needs its own terms
In March, Monument said deposits were the first phase and that it would explore tokenized investments and new lending options within its app afterward.
The current saver’s published terms do not provide an investment-backed lending facility. For investment-backed lending, the relevant terms would need to identify the collateral, establish the lender’s rights over it and explain how customers obtain spendable funds.
Customer-controlled transfers or external token collateral would also require rights and arrangements beyond this saver’s present restrictions.
For savers today, the concrete offer is fixed interest and an additional bank-controlled record, while future customer liquidity depends on new product rights and operating arrangements. Disclosure of the funded and tokenized balance would answer the separate question of the program’s scale.
Mentioned in this article
Editorial credits
Also known as "Akiba," Liam Wright is a reporter, podcast producer, and Editor-in-Chief at CryptoSlate. He believes that decentralized technology has the potential to make…
Gino Matos is a law school graduate and a seasoned journalist with six years of experience in the crypto industry. His expertise primarily focuses on the Brazilian blockchain…