Bitcoin traders face Friday’s $2.7 billion options expiry with a dangerous five-hour blind spot
Quick Take
- Bitcoin faces a $2.7 billion options expiry Friday, with a $79,000 max-pain level sitting below its $80,000 trading price.
- Nearly 75% of expiring contracts are calls, while the options settle 5.5 hours before the US jobs report, creating a potential hedging gap.
- Traders face a 74% premium for puts extending through payrolls, as the jobs data threatens to reshape Fed expectations and Bitcoin's recovery.

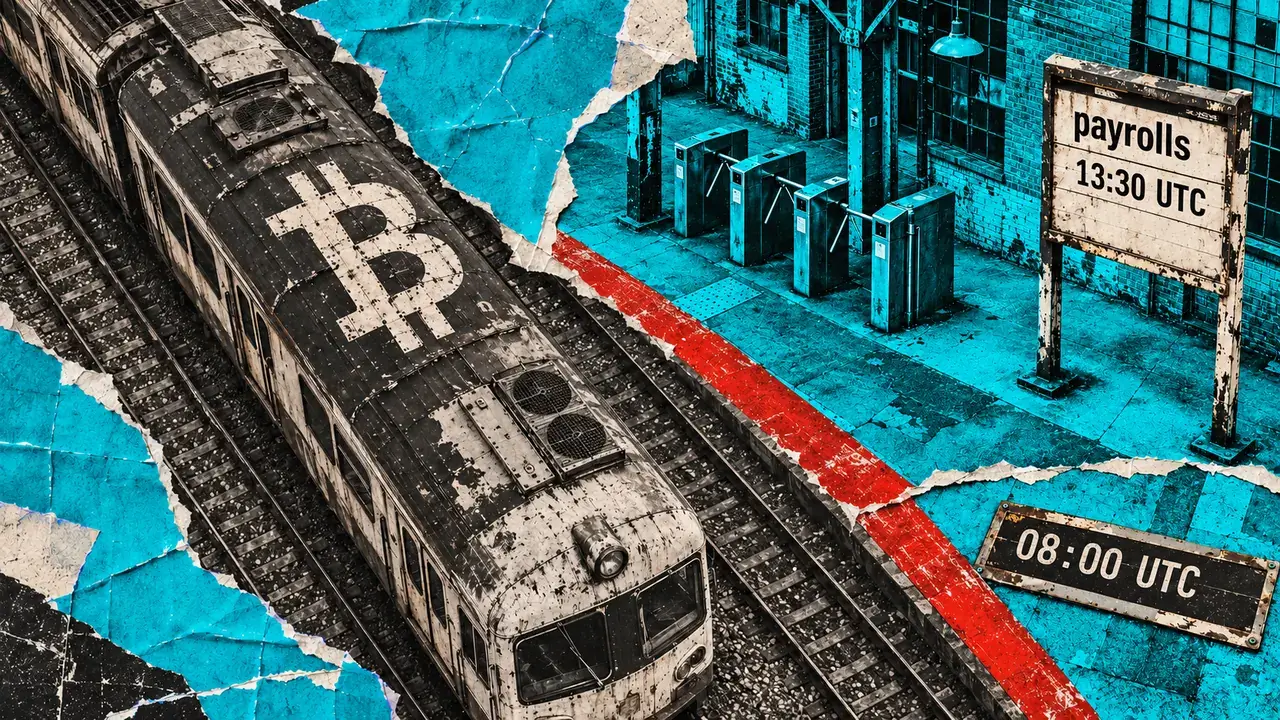
Bitcoin options worth approximately $2.7 billion expire Friday, five and a half hours before the US jobs report.
Data from Deribit shows 33,441 BTC in outstanding options contracts scheduled to expire at 08:00 UTC on Nov. 6, with the calculated maximum pain price sitting at $79,000.
The level is approximately 1.6% below Bitcoin's $80,280 current price, placing the expiry near the cryptocurrency's current trading range as investors prepare for another potential shift in US interest-rate expectations.
The contracts are heavily skewed toward bullish call options, which account for approximately 25,012 BTC in open interest, compared with 8,429 BTC in puts. That puts the put-to-call ratio at 0.34, with nearly three calls outstanding for every put.
The largest concentrations of call open interest sit at the $82,000 and $85,000 strike prices, while significant put positions are clustered between $72,000 and $75,000.
Deribit BTC call and put open interest for the Nov. 6, 2026 expiry. Approximate values digitized from a user-supplied Nov. 5 screenshot and rounded to 100 BTC. Very small or unreadable bars are missing (null), not zero; omitted strike labels also had no sufficiently legible bars. The screenshot marks $79,000 as max pain, not a price forecast. Intrinsic value is omitted because it uses a separate USD axis. Historical strike counts could not be checked independently.
 CryptoSlate
Source: Deribit, BTC options open interest (user-supplied screenshot; estimates, Nov. 5, 2026) · XOOMAR, Deribit-based Nov. 5 snapshot (max pain and expiry-wide open interest cross-check only)
View dataHide data| Category | Calls | Puts |
|---|---|---|
| $65,000 | Not reported | 200 BTC |
| $68,000 | Not reported | 200 BTC |
| $70,000 | Not reported | 700 BTC |
| $72,000 | Not reported | 800 BTC |
| $73,000 | Not reported | 600 BTC |
| $74,000 | Not reported | 1,200 BTC |
| $75,000 | Not reported | 1,000 BTC |
| $75,500 | Not reported | 200 BTC |
| $76,000 | 100 BTC | 700 BTC |
| $77,000 | 200 BTC | 400 BTC |
| $77,500 | 100 BTC | Not reported |
| $78,000 | 400 BTC | 500 BTC |
| $78,500 | 200 BTC | Not reported |
| $79,000 | 1,200 BTC | 200 BTC |
| $79,500 | 200 BTC | 100 BTC |
| $80,000 | 2,300 BTC | 400 BTC |
| $81,000 | 700 BTC | 400 BTC |
| $82,000 | 6,200 BTC | 400 BTC |
| $83,000 | 900 BTC | Not reported |
| $84,000 | 400 BTC | Not reported |
| $85,000 | 5,200 BTC | Not reported |
| $86,000 | 300 BTC | Not reported |
| $87,000 | 200 BTC | Not reported |
| $88,000 | 600 BTC | Not reported |
| $90,000 | 2,800 BTC | Not reported |
| $95,000 | 2,300 BTC | Not reported |
| $100,000 | 300 BTC | Not reported |
The $79,000 maximum pain level represents the settlement price at which outstanding options would collectively generate the lowest intrinsic-value payout. Although traders monitor the figure ahead of expiration, it does not guarantee that Bitcoin will gravitate toward that price.
Likewise, the $2.7 billion figure represents the notional value of outstanding contracts rather than money expected to enter or leave the market. Actual settlement outcomes depend on Bitcoin's price and how traders manage their positions.
However, Friday's expiry adds another layer of complexity because of its timing relative to the next major US economic release.
Bitcoin traders face higher costs to hedge US jobs report
The Bureau of Labor Statistics will release October's employment report at 08:30 a.m. Eastern, or 13:30 UTC on Nov. 6, five and a half hours after Deribit's options settle.
That creates a potential protection gap for traders relying on Friday-expiring put options to hedge against a sudden Bitcoin sell-off.
Under Deribit's settlement rules, the contracts expire using Bitcoin's average index price between 07:30 and 08:00 UTC. Consequently, any price reaction to the subsequent employment report falls outside their protection period.
Investors seeking coverage through the announcement would therefore need longer-dated contracts or alternative hedges.
Deribit's Nov. 5 order book illustrated the additional cost. An $80,000 Bitcoin put expiring Nov. 6 carried an asking premium of approximately $393 per BTC of exposure, compared with $682 for the equivalent strike expiring Nov. 7.
| Expiry, 08:00 UTC | Scheduled releases before expiry | Ask in BTC | Approximate USD |
|---|---|---|---|
| November 6 | Neither payrolls nor CPI | 0.0049 | $393 |
| November 7 | Payrolls | 0.0085 | $682 |
| November 13 | Payrolls and CPI | 0.0180 | $1,445 |
The latter contract was roughly 74% more expensive, although the difference also reflects its additional trading duration and other market-pricing factors.
Protection extending through the Nov. 10 inflation report was even costlier, with an $80,000 put expiring Nov. 13 quoted at approximately $1,445.
Friday's expiry ends before the jobs report
Choose an expiry to see which scheduled releases occur while the put is still live.
Which releases happen before this put expires?
Expires before payrolls and CPI.
The November 6 put expires before payrolls; November 7 spans payrolls, and November 13 spans payrolls and CPI.
All macro releases are scheduled future events. A live European put does not guarantee a payout from a temporary drop; settlement depends on its delivery price. These diagrams do not describe holders' other hedges or predict prices.
Sources
Supporting facts
- The BLS November calendar schedules the October Employment Situation report for November 6 at 08:30 Eastern, or 13:30 UTC, five and a half hours after these Deribit options expire; October CPI is scheduled for November 10 at 08:30 Eastern, also 13:30 UTC. [1] [2] [4] [5]
- Deribit inverse BTC options are European-style and settle in BTC. Their delivery price uses the index's 07:30 to 08:00 UTC time-weighted average; since August 1, 2026, in-the-money options settle through an expiring inverse future, with the same net result as direct cash settlement. [3]
- The November 7 $80,000 put expires at 08:00 UTC after payrolls but before CPI, while the November 13 $80,000 put expires at 08:00 UTC after both scheduled releases; the November 6 put expires before either. [1] [2] [3]
Method
Compare instrument expiry timestamps with the BLS calendar. Eastern is UTC-5 on these dates. 13:30 minus 08:00 equals 5h30m. The detailed Friday interval shows that gap; selectable diagrams show event order only, not elapsed-time distances.
Scope
All macro releases are scheduled future events. A live European put does not guarantee a payout from a temporary drop; settlement depends on its delivery price. These diagrams do not describe holders' other hedges or predict prices.
 CryptoSlate
Those prices provide a snapshot of the cost of buying new protection rather than the actual expense of rolling existing positions, which depends on available bids, liquidity, and execution.
The timing comes as investors assess whether the US labor market is weakening enough to influence the Federal Reserve's next monetary policy decision.
Analysts at Bitunix said markets expect the economy to have added 65,000 jobs in October, with the unemployment rate unchanged at 4.2%.
The analysts argued that stable employment would give the Fed greater flexibility to assess inflation before adjusting interest rates, while a significant deterioration could increase expectations of a more accommodative policy stance.
A stronger-than-expected employment report could instead reinforce concerns about persistent inflation and restrictive monetary policy, potentially putting pressure on Bitcoin through higher Treasury yields and a stronger dollar.
The upcoming report follows Bitcoin's recovery above $80,000 after its recent decline, leaving traders to assess whether improving market sentiment can withstand another macroeconomic shock.
Friday's sequence will provide two separate tests. The 08:00 UTC settlement will resolve the outstanding options positions, while the employment report later that morning will determine whether traders need to reposition for a changed interest-rate outlook.
With October's inflation figures due Nov. 10, demand for longer-dated protection could remain sensitive to how sharply Friday's payrolls data changes market expectations.
Mentioned in this article

Editorial credits
Oluwapelumi values Bitcoin's potential. He imparts insights on a range of topics like DeFi, hacks, mining and culture, underlining transformative power.