Bitcoin’s inflation hedge has a hidden cost, and leverage makes it worse
Quick Take
- High inflation can strengthen Bitcoin's appeal while keeping borrowing costs elevated.
- Cash buyers, borrowers, and futures traders face different costs for holding Bitcoin.
- Investors can predict Bitcoin's price correctly and still lose money to financing costs.

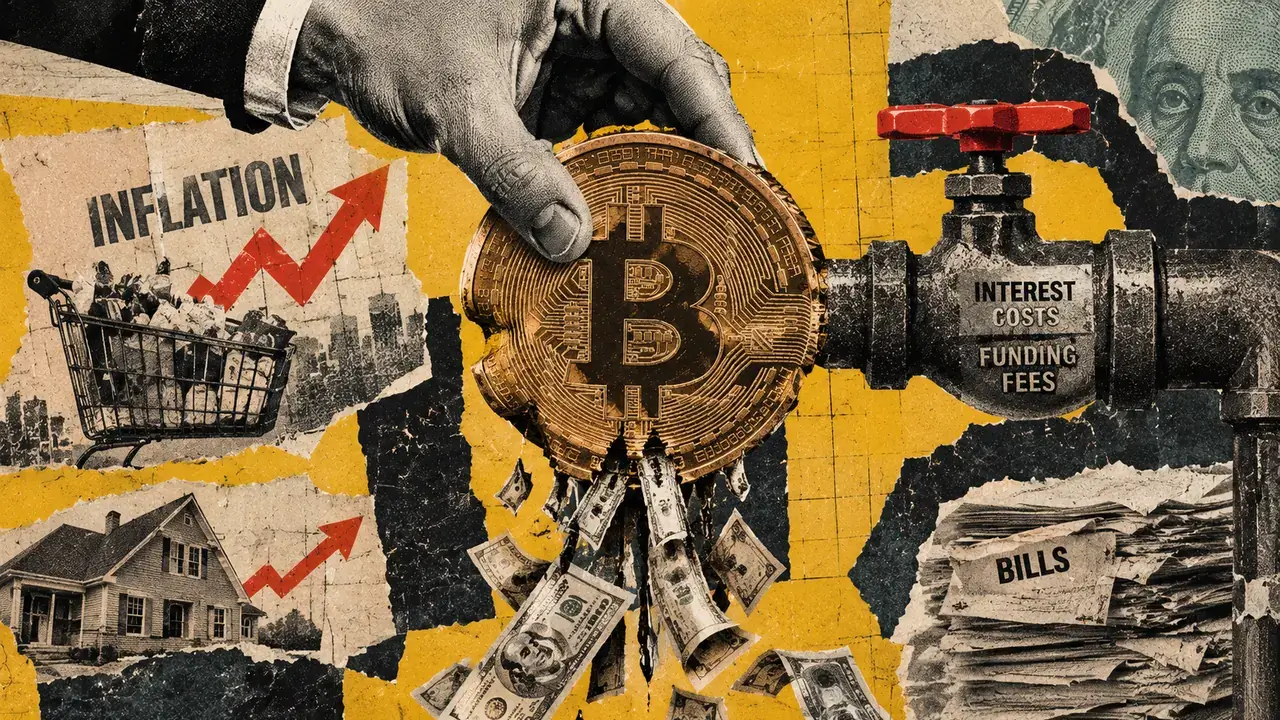
Borrowing costs, missed interest income, and futures fees can all eat into returns even when Bitcoin holds its value. That's a big problem, and it gets even worse when inflation stays high.
September's US inflation report showed consumer prices up 3.7% year over year, fueling concerns about the dollar's purchasing power. That same inflation pressure keeps interest rates high, making it more expensive to borrow money to buy Bitcoin and hold it while waiting for it to rise.
Bitcoin reacted immediately to the inflation report, but the bigger question now is what happens next. Two people or companies can buy Bitcoin at the same price, hold it for the same period, and walk away with very different returns, all because they financed their purchases differently.
One Bitcoin bet, three different bills
Someone who buys $10,000 of Bitcoin with cash has no interest payments to make while holding it. The coins can rise or fall in price without a lender demanding repayment.
The Federal Reserve's interest-rate release showed a 4.26% three-month Treasury constant-maturity yield for Oct. 13, the day before the CPI report. While that's an annualized market benchmark, it still illustrates what we call opportunity cost. If $10,000 could earn 4.26% for an entire year, the return would be $426 before taxes.
If Bitcoin ended the year at the same price it was bought for, its holder would have no trading loss, but they would have missed that hypothetical alternative return. So even though cash buyers don't get an interest bill, choosing a non-yielding asset has an economic cost when other investments offer income.
Now consider another investor with the same $10,000 who borrows an additional $10,000 at a hypothetical 8% annual rate and buys $20,000 of Bitcoin.
The investor has doubled the exposure and also accepted an $800 annual interest obligation. If Bitcoin ends the year at the same price, selling the position and repaying the $10,000 loan plus $800 interest leaves him with $9,200.
The first investor breaks even before fees, and the second loses 8% of their own capital without Bitcoin falling at all.
That difference becomes easier to see across several possible outcomes:
| Bitcoin's one-year price change | $10,000 cash purchase: ending value | $20,000 purchase with $10,000 loan: equity after repayment |
|---|---|---|
| −10% | $9,000 | $7,200 |
| 0% | $10,000 | $9,200 |
| +10% | $11,000 | $11,200 |
Hypothetical one-year outcomes. Both investors start with $10,000 of their own money. The borrower pays 8% interest on a $10,000 loan. Figures exclude taxes, fees, and any early liquidation.
The leveraged investor needs Bitcoin to jump 4% just to cover the $800 interest bill. Matching the cash investor's illustrative $426 alternative return would require a 6.13% Bitcoin gain.
At a 10% price increase, leverage helps the borrower earn more than the cash buyer. But at a 10% decline, it makes the loss substantially worse.
And the table assumes something real markets don't always allow: that the borrower gets to hold the position for a full year.
If Bitcoin falls sharply along the way, a lender can demand additional collateral or liquidate a position before the eventual recovery arrives. Investors may be right about where Bitcoin finishes and still be unable to remain invested long enough to benefit.
Futures can hide the cost in the entry price
Bitcoin futures can easily obscure leverage, making the financing charge less obvious.
Dated futures contracts let traders take on Bitcoin exposure at a price agreed today for settlement later. That price can be above the current spot price, creating what traders call the futures basis.
Suppose Bitcoin trades for $80,000 in the spot market while a contract settling in 90 days trades for $81,200.
The $1,200 premium equals 1.5% of the spot price, or about 6.08% annualized. If Bitcoin's spot price is still $80,000 at settlement, the long futures position loses $1,200 per Bitcoin of exposure as the contract converges toward the underlying price.
The trader never had to take out a loan to experience that difference, because the premium was embedded in the entry price.
This is where we start to see the connection to interest rates. Traders who buy spot Bitcoin and sell a more expensive future may need to borrow to fund the spot purchase, so inflation, which affects the cost of dollar financing, can influence that premium.
Future prices also reflect the demand for leveraged exposure, and show the capital available for arbitrage. They also reflect the trading constraints investors face when dealing with derivatives.
Spot and futures observations need to be matched in time before their difference means anything. A premium calculated from unrelated price snapshots can easily describe a trade nobody could execute.
Unlike dated contracts, perpetual futures have no scheduled expiry, and exchanges use funding payments to keep their prices near a reference market.
Under Deribit's published rules, positive funding means long positions pay short positions, while negative funding means shorts pay longs.
That makes funding different from a fixed borrowing rate. It can rise, fall, or change direction depending on how traders are positioned. Government borrowing costs can remain high while perpetual funding turns negative during a market sell-off.
Neither a Treasury yield nor an annualized funding quote tells an investor the full cost of a derivatives position by itself.
Collateral can earn interest, depending on the venue and how the account is funded. Margin requirements can change, trading fees matter, and funding payments must be measured over the actual holding period.
A careful calculation also avoids charging the same financing expense twice. The price difference built into a dated future and the separate cost of borrowing to fund collateral are not automatically two complete versions of the same loan bill.
An inflation hedge isn't the same as an inflation adjustment
Bitcoin's long-term scarcity case is often presented as protection against currencies losing purchasing power. Its supply is capped at 21 million coins, and investors such as Michael Saylor have helped make that argument central to corporate Bitcoin ownership.
But the supply cap doesn't mean its price rises when CPI increases.
Inflation measures changes in the prices people have already paid for goods and services, while Bitcoin's return depends on what future buyers are willing to pay. Those are different processes, even if investors believe the former will eventually strengthen demand for the latter.
Treasury Inflation-Protected Securities (TIPS) adjust their principal with changes in the relevant inflation index, and the security's terms include the inflation adjustment.
The ten-year inflation-indexed Treasury had a constant-maturity yield of 2.88% on Oct. 13. That's a useful benchmark, though an investor selling a TIPS early can still lose money if market yields rise and the security's price falls.
Investors can compare several assets with different income streams, inflation exposures, liquidity needs, and market risks.
A Bitcoin holder is not necessarily wrong about the eventual effect of inflation, but future appreciation must be large enough to justify what holding the position costs along the way.
The appeal of Bitcoin's limited supply doesn't depend on a single monthly inflation report, nor can one strong CPI reading prove that Bitcoin will outperform cash, bonds, or other assets over the next several years.
Higher borrowing costs change how long some investors can afford to wait for that outcome.
Cash buyers can hold through a disappointing year, accepting the income forgone elsewhere. Borrowers must find the interest money and maintain enough collateral to avoid being closed out, while futures traders must manage the contract's premium, funding, margin requirements, and eventual exit.
All of them can see the same future for Bitcoin but end up with very different results.
Bitcoin might recover from an ugly decline and finish above the original purchase price, yet the leveraged investor who was liquidated during the fall will see none of that recovery.
Inflation can strengthen the case for owning Bitcoin, but expensive financing can shorten the time available to prove that case right.
Bitcoin is -0.73% over the past 24 hours and currently sits at rank #1 by market cap.
Mentioned in this article

Editorial credits
Armed with a classical education and an eye for news, Andjela dove head deep into the crypto industry in 2018 after spending years covering politics.

Gino Matos is a law school graduate and a seasoned journalist with six years of experience in the crypto industry. His expertise primarily focuses on the Brazilian blockchain…